How to Protect Your Bank Accounts from AI Scams
Discover essential strategies to safeguard your bank accounts from AI scams and ensure your financial security.
Navigate your 2026 mortgage offer with our detailed guide and checklist to make informed financial decisions.
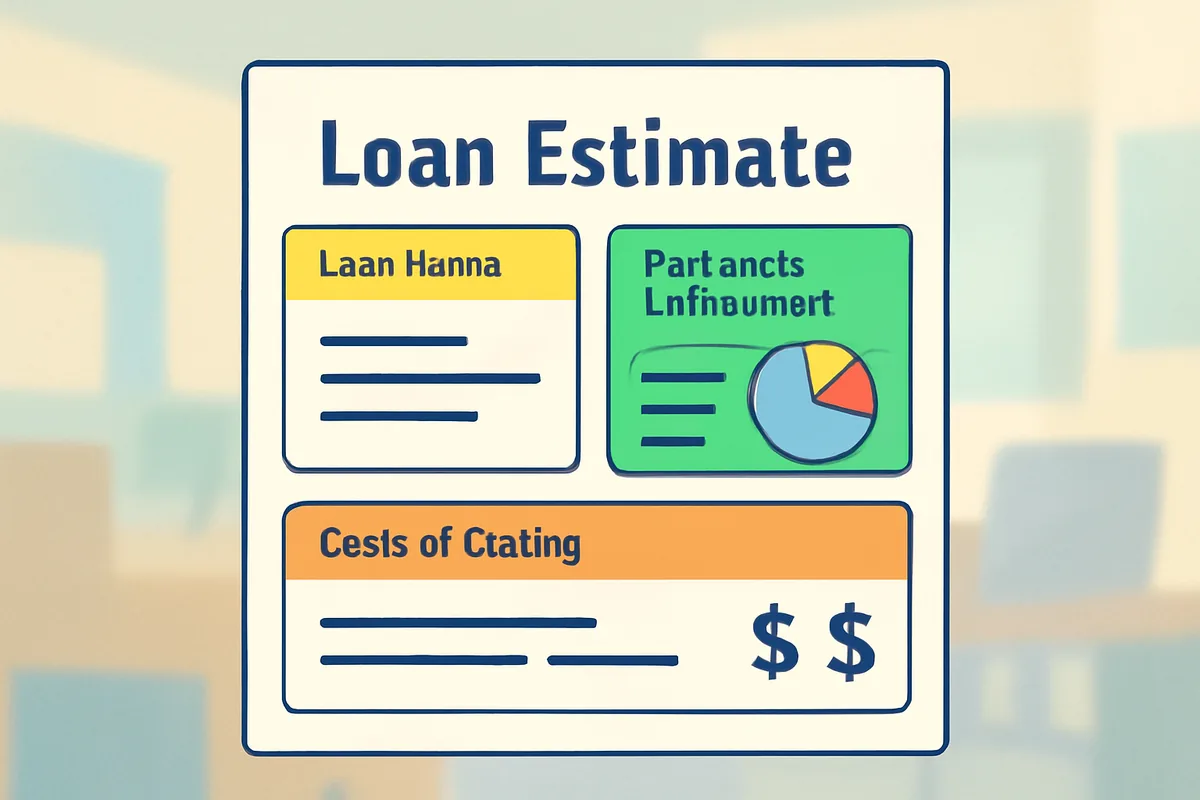
A mortgage offer, often preceded by a Loan Estimate, is a crucial document that outlines the terms of a mortgage loan. It's essentially the lender's formal commitment to offer you a loan under specific terms. In 2026, this document includes critical details such as the loan amount, interest rates, closing costs, and other important conditions. The Loan Estimate is a standardized form introduced to help borrowers compare offers from different lenders easily, ensuring they can evaluate and choose the best mortgage option for their needs.
The Loan Estimate is a standardized three-page form that lenders must provide within three business days of your application. It is structured to provide clarity and ease of comparison among different loan offers. Key sections include:
Focus on the interest rate, monthly payments, and Annual Percentage Rate (APR) for effective comparisons. The APR is particularly vital as it reflects the total cost of the loan, including fees, making it easier to assess the true cost of borrowing [1][3].
When evaluating a mortgage offer in 2026, pay close attention to the following components:
To make an informed decision, obtain Loan Estimates from at least three different lenders. Each offer should be scrutinized based on several key factors:
Negotiation is key. Lenders might offer different rates and terms, so shopping around can lead to significant savings over your loan's lifetime [1][3][6]. For instance, on a $400,000 loan, a 0.50% rate difference could equate to a $32,000 difference over 30 years.
Navigating mortgage documents can be complex. Consulting a mortgage advisor or legal professional can be invaluable, especially if your offer includes unique or unusual elements. These experts can explain terms you’re unsure about and help identify potential red flags.
Once you've chosen a lender, you will move on to the next step: reviewing the Closing Disclosure. This document finalizes your loan terms and costs. By law, you should receive it three days before closing. This window provides an opportunity to compare it with your Loan Estimate to ensure no unexpected changes have been made [3][5].
A mortgage offer is a document outlining the terms of a mortgage loan, including loan amount, interest rates, and closing costs. It is often preceded by a Loan Estimate, which helps you compare offers from different lenders.
A Loan Estimate is a standardized three-page form provided by lenders within three business days of your application. It includes loan terms, projected payments, and costs at closing. Focus on the interest rate, monthly payments, and APR for effective comparisons.
In a mortgage offer checklist, look for interest rates, APR, fees, ARM details if applicable, loan terms, and closing costs. Understanding these elements helps you make informed decisions and negotiate better terms.
To compare mortgage offers effectively, obtain Loan Estimates from at least three lenders. Compare loan amounts, interest rates, APR, monthly payments, and closing costs. Ensure all loan terms are consistent across offers to make accurate comparisons.
More from Money & Finance.
Discover essential strategies to safeguard your bank accounts from AI scams and ensure your financial security.
Discover if Citigroup stock is undervalued in 2026 with insights into valuation models and market conditions.
Explore how the Florida Lottery operates, including ticket purchasing, prize claiming, and tax implications in 2026.